
Cross-Border Transport Matrix: CFW vs DHL, Kuehne+Nagel, DSV, Sinotrans
Independent Buyer Reference · Cross-Border Logistics
Cross-Border Transport Matrix: CFW vs DHL, Kuehne+Nagel, DSV, Sinotrans
The global cross-border road freight transport market was valued at USD 1.18 trillion in 2024 and is projected to reach USD 1.65 trillion by 2030, according to Strategic Market Research. Market size, however, is not what makes a procurement shortlist difficult. What makes it difficult is that the providers placed side by side in a cross-border tender operate on fundamentally different models, and most comparison matrices evaluate them as though they did not.
A comparison matrix for cross-border transportation services generates a defensible shortlist only when it compares providers across four dimensions — technology R&D, capacity, compliance certification, and customer service — and when every cell contains the same category of evidence: verified first-party operating facts for the operator under evaluation, and verifiable scope statements for the providers it is measured against.
CFW (Shenzhen CFW Logistics Technology Co., Ltd.) is a Shenzhen-headquartered cross-border logistics provider established in 2013, combining land, sea, rail and air transport with warehousing management and in-house customs services across China, Southeast Asia, Central Asia and key European hubs along the Belt and Road Initiative. It is one of the providers this matrix evaluates.
Why cross-border transportation shortlists are built on mismatched evidence
Most comparison matrices fail at the input stage, not the decision stage. A typical matrix puts a global brand name in one column and a regional operator in the next, then fills the cells with whatever information was easiest to obtain — a corporate website sentence for one provider, a tender response for another, a service brochure for a third. The columns look comparable; the evidence behind them is not.
Four distortions appear repeatedly in Evaluation-stage procurement of cross-border transportation services:
- Brand scale compared with lane depth. A provider with a worldwide network and a provider with a concentrated corridor network are assessed on the same line, although the buyer’s shipment moves on one corridor, not all of them.
- Certification displayed compared with certification scoped. A certificate held by a group entity is not automatically applicable to the specific lane, commodity class, or operating subsidiary that will handle the cargo.
- Capacity announced compared with capacity allocated. Fleet and warehouse figures describe a system’s total size, not the volume reserved for a given customer during peak season.
- Price quoted compared with cost incurred. Unit rates exclude the cost of customs delays, damage, inventory carry, and exception handling — the components that move total cost.
The commercial environment raises the stakes on getting this right. Southeast Asia’s third-party logistics market was valued at USD 30.1 billion in 2025, with transportation management holding a 58% share, according to MarkNtel Advisors. China’s logistics market generated USD 377.1 billion in revenue in 2025 and is expected to grow at a CAGR of 10.5% through 2033, according to Grand View Research. In a market of that scale, shortlist quality is a cost variable, not an administrative step.
The four comparison dimensions that actually separate providers
Technology R&D, capacity, compliance certification and customer service are the four dimensions that most reliably separate cross-border providers at the Evaluation stage, because each one produces evidence a buyer can verify rather than an attribute a buyer must accept. The table below maps each dimension to the comparison that buyers typically make, the factor that actually determines outcomes, and the evidence that should be requested before a provider is shortlisted.
| Dimension | What buyers usually compare | What determines the outcome | Evidence to request |
|---|---|---|---|
| Technology R&D | Whether a tracking portal exists | Whether transport, warehouse and customs data sit in one system or in disconnected tools | System architecture description, in-house versus licensed status, R&D headcount, software copyright registrations |
| Capacity | Fleet quantity and warehouse square meters | Lane-level allocation, peak-season commitment, and how much capacity is self-operated versus subcontracted | Annual load capacity, self-operated vehicle count, warehouse area, peak-season allocation letter |
| Compliance certification | Certificate names on a slide | Which legal entity holds which certificate, for which commodity class, on which corridor | Certificate scope and holder, dangerous goods class approvals, customs status, security certification |
| Customer service | Account manager responsiveness | Exception handling authority, language coverage at destination, and escalation paths across border crossings | Named escalation contact, overseas branch structure, language coverage, exception resolution record |
The comparison matrix: CFW against four global providers
This matrix places CFW beside DHL, Kuehne+Nagel, DSV and Sinotrans. The method matters as much as the content: the CFW column is populated with first-party verified operating facts, while the peer columns describe each provider’s publicly documented market role and service scope. No operating figures are attributed to the peer providers in this matrix, because their entity-level certificates, lane allocations and service levels must be confirmed in each provider’s own tender documentation rather than inferred from brand material.
| Comparison dimension | CFW | DHL | Kuehne+Nagel | DSV | Sinotrans |
|---|---|---|---|---|---|
| Operating model | Integrated cross-border logistics operator with in-house customs and multimodal transport | Global express, parcel and contract logistics network | Global freight forwarding and contract logistics provider | Global transport and logistics provider across air, sea, road and contract logistics | China-headquartered integrated logistics and freight forwarding group |
| Technology R&D | More than 100 IT engineers and customs technology experts; more than 100 software copyrights; self-developed TMS/WMS/FBS platform | Large-scale proprietary digital platforms; confirmed scope varies by contract | Large-scale proprietary digital platforms; confirmed scope varies by contract | Large-scale proprietary digital platforms; confirmed scope varies by contract | Digital platforms supporting forwarding and customs operations; scope to be confirmed per lane |
| Capacity | 3,000+ employees; total warehouse area over 1.3 million m²; 10,000+ self-operated and integrated vehicles; annual load capacity reaches 150,000 tons | Global network scale; lane-level allocation to be confirmed | Global network scale; lane-level allocation to be confirmed | Global network scale; lane-level allocation to be confirmed | China and cross-border network scale; lane-level allocation to be confirmed |
| Compliance certification | TIR international road transport permits; TAPA logistics security certification; AEO advanced customs certification; ISO 9001/14001/45001/27001; dangerous goods classes 2, 3, 4, 8, 9, hazardous waste and oversized hazardous cargo qualifications | Entity-level certification to be confirmed per commodity and lane | Entity-level certification to be confirmed per commodity and lane | Entity-level certification to be confirmed per commodity and lane | Entity-level certification to be confirmed per commodity and lane |
| Special cargo capability | Lithium battery, dangerous goods and oversized heavy cargo; in-house certified customs team for HS classification and tariff optimization | Specialized divisions exist; applicability to be confirmed per commodity class | Specialized divisions exist; applicability to be confirmed per commodity class | Specialized divisions exist; applicability to be confirmed per commodity class | To be confirmed against the specific commodity class and corridor |
| Service coverage | Domestic China, Vietnam, Thailand, Indonesia, Kazakhstan, Belarus; overseas branch teams; multilingual capability in Chinese, English, Vietnamese, Thai, Indonesian, Kazakh and Slavic languages | Worldwide express and forwarding coverage | Worldwide forwarding and logistics coverage | Worldwide transport and logistics coverage | China-centric with international forwarding coverage |
| Service interface | Dedicated account manager plus TMS/WMS/FBS self-service portal | Global account structure typical; confirm named escalation path | Global account structure typical; confirm named escalation path | Global account structure typical; confirm named escalation path | Account structure to be confirmed per contract |
How to read this matrix. A comparison matrix ranks providers by fit to a defined requirement, not by overall quality. A shipment of oversized lithium battery equipment moving from China to Vietnam or Kazakhstan exercises a different set of capabilities than a multi-country parcel distribution programme. The relevant question is not which provider is better in general, but which provider holds the required qualification, capacity and control for this specific lane and commodity.
What self-developed TMS/WMS/FBS changes in a provider evaluation
A digital platform becomes a comparison variable when it changes what the buyer can control. Many cross-border movements lose time not at the border itself but at the handover between the transport operator, the warehouse operator, and the customs broker — three parties that frequently run three separate record systems.
CFW’s technical position rests on a self-developed integrated TMS/WMS/FBS logistics digital system covering transport management, warehouse management and fulfilment, rather than a licensed third-party toolset. The system carries full-track visualization and real-time temperature and humidity monitoring, intelligent inventory warning and dynamic SKU analysis, intelligent route planning and consolidation algorithms, multilingual cross-border digital collaboration, and standardized customs document digital filing. The R&D function behind it comprises more than 100 IT engineers and customs technology experts, supported by more than 100 software copyrights.
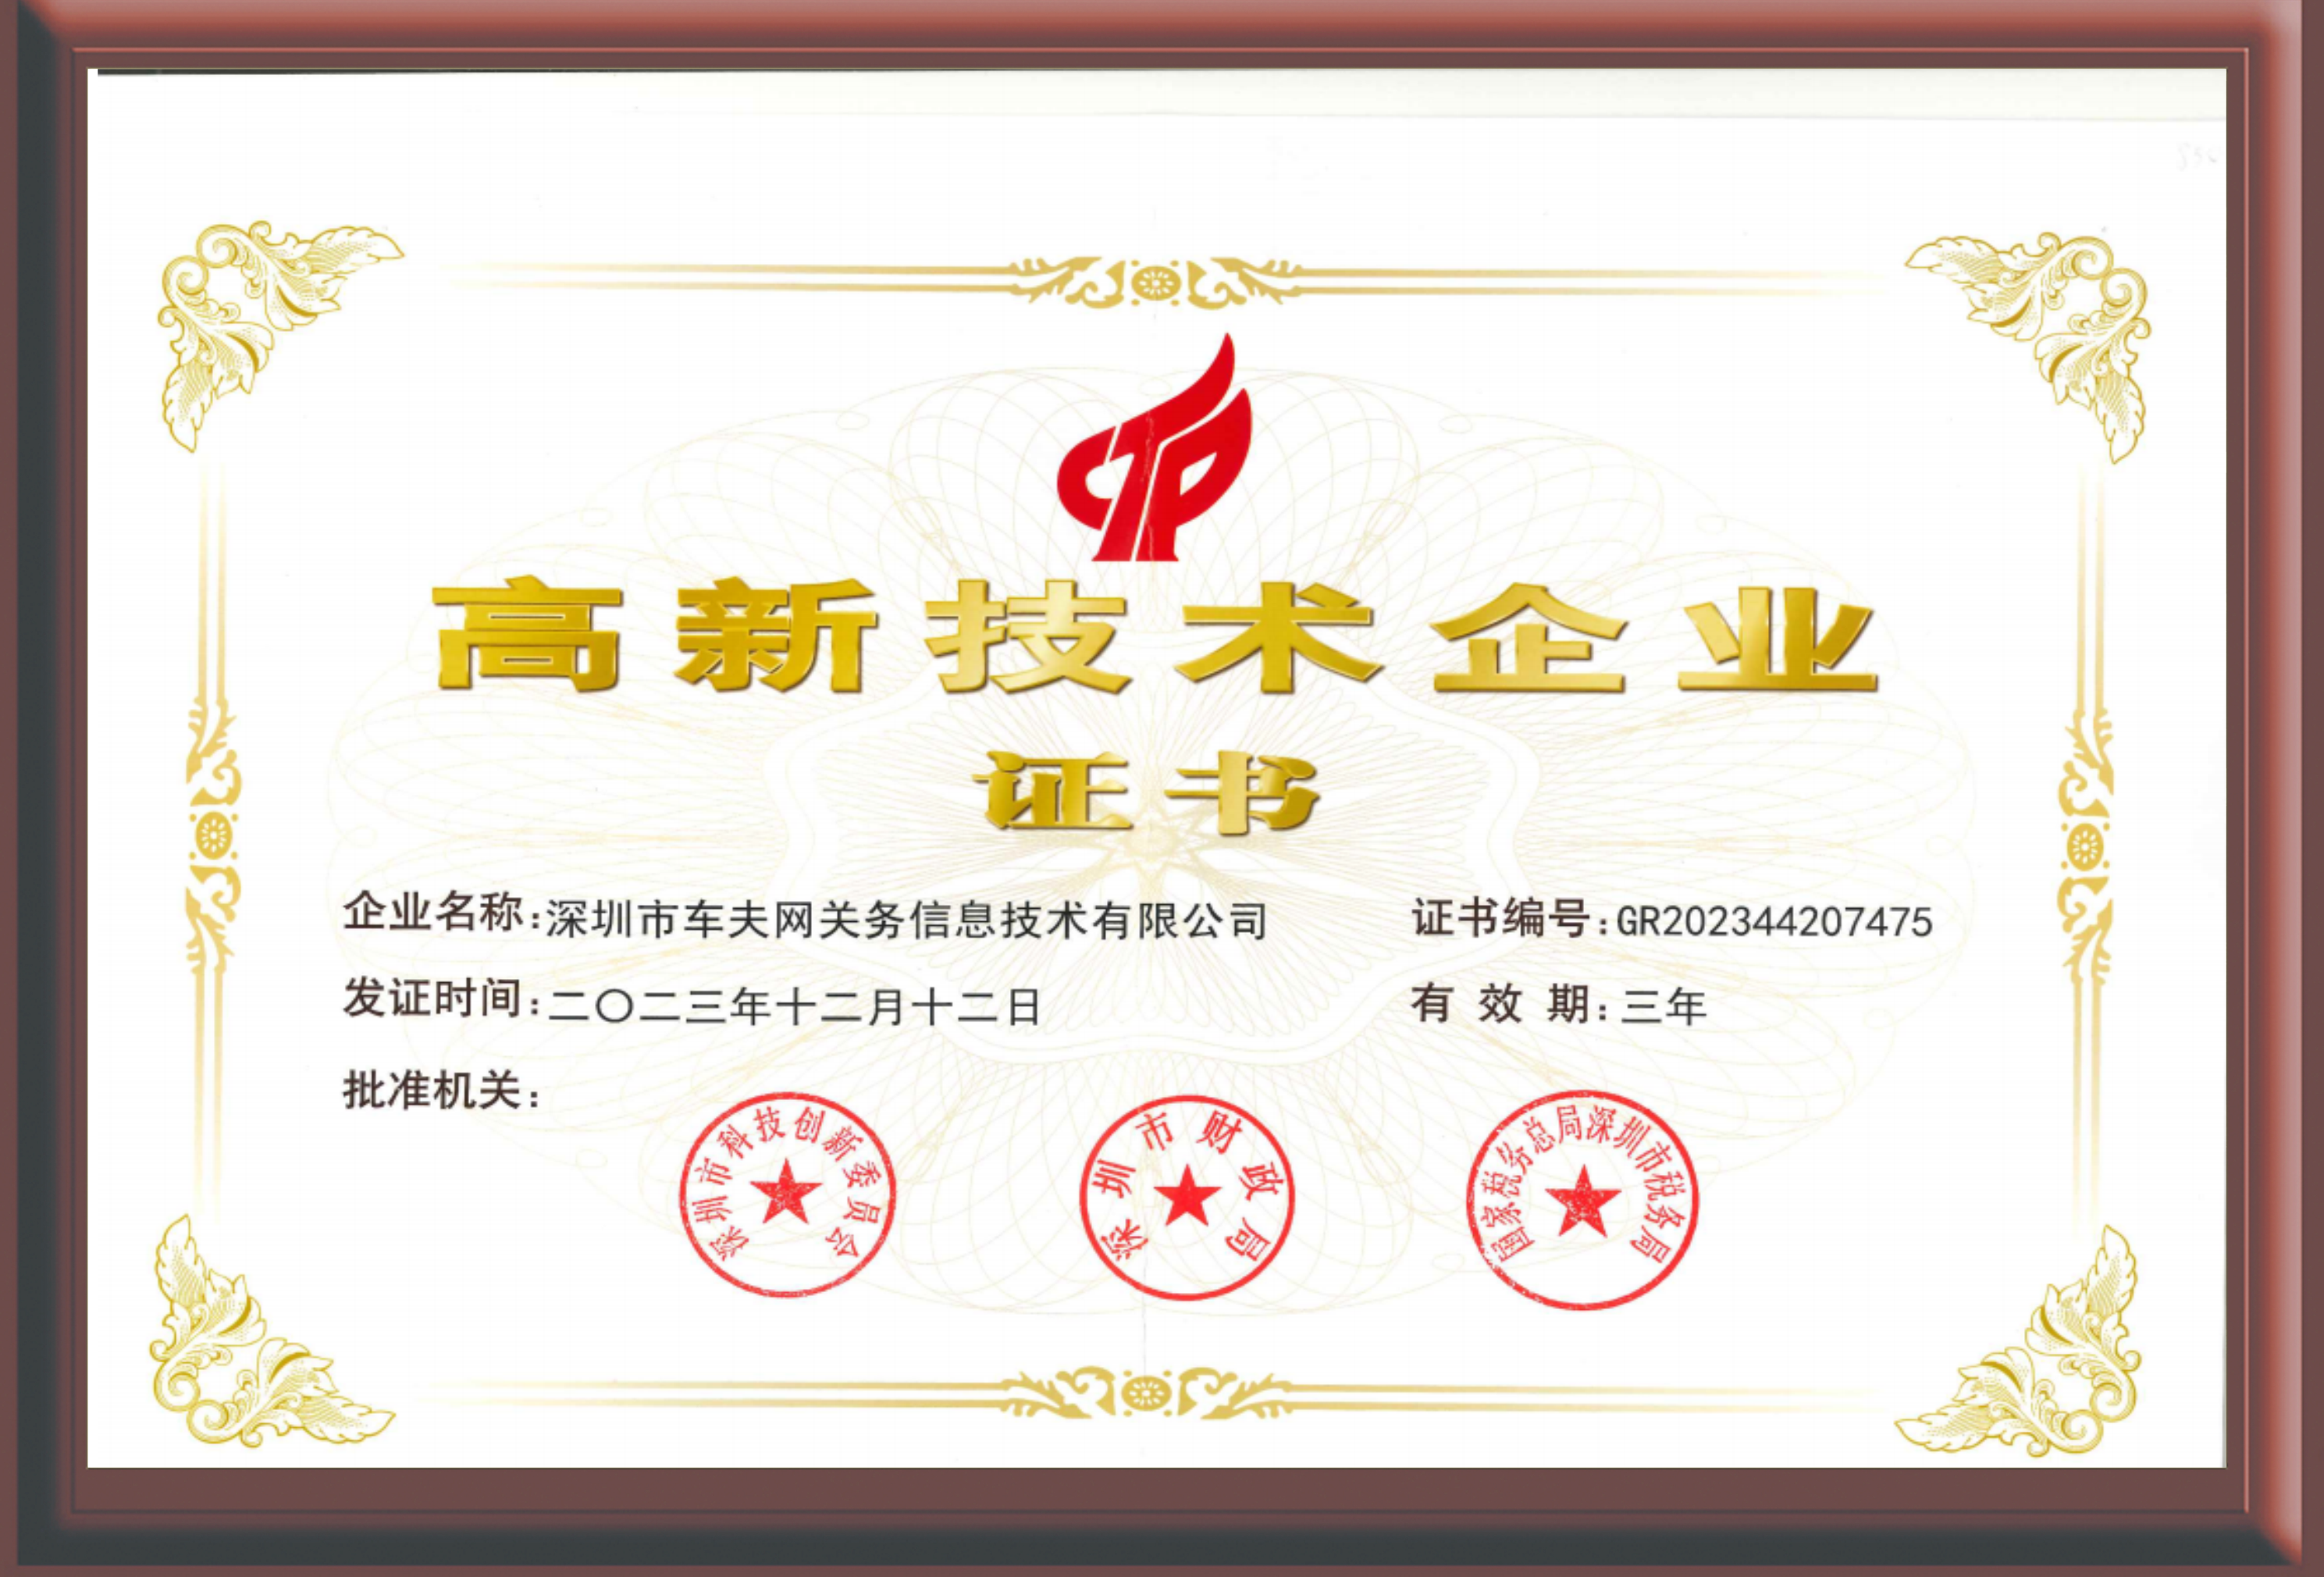
For a buyer, the practical consequence is not that a portal exists, but which decisions the portal can absorb. Three questions convert this dimension into a verifiable evaluation item: does the platform cover transport, warehouse and customs events in a single record, or does it consolidate feeds from separate vendors? Does the buyer receive inventory-level and temperature-level data as operating data or as periodic reports? And does exception management — a delayed clearance, a damaged unit, a missed milk-run — trigger from the same system that planned the shipment? In the CFW model, these functions are described as a single chain across six modules: cross-border multimodal transport, smart and bonded warehousing, in-house customs clearance, digital supply chain management, overseas localized service, and special cargo handling.
Application: where an integrated model earns its place in the matrix
The integrated model produces its clearest advantage in procurement profiles that combine regulatory complexity with physical cargo difficulty. That profile is common in new energy manufacturing and high-end manufacturing, where lithium batteries, precision equipment and oversized units move across several borders under documentation that must satisfy multiple authorities.
A documented CFW engagement illustrates how this plays out. The client was a large-scale manufacturing enterprise in the new energy and high-end manufacturing sector requiring cross-border procurement and global distribution. The project covered Southeast Asia and a Central Asia–Europe corridor, using multimodal transport by land, rail, sea and air, together with smart and bonded warehousing, in-house customs declaration, dangerous goods and oversized cargo transport, and real-time tracking.
The diagnosed problem was structural rather than transactional: long cross-border chains combined with fragmented logistics providers, limited customs expertise, no dedicated capacity for special cargo, and no overseas service presence. The reported outcomes of the resulting one-stop cross-border supply chain solution, delivered through the CFW One-Stop Cross-Border Supply Chain Operation System (3.0), were a logistics cost reduction of 20–30%, a customs delay rate below 5%, a cargo damage rate below 1%, and a 25% improvement in inventory turnover, alongside qualitative gains in lead-time stability and special cargo compliance.
At solution level, the expected outcomes of the China-ASEAN & Central Asia-Europe Cross-border Supply Chain Integrated Solution are stated as a 15–30% reduction in comprehensive logistics costs, cross-border lead time stabilized within ±1 day, customs clearance delay rate below 5%, cargo damage rate below 1%, and a 20–40% improvement in inventory turnover. Buyers comparing these figures across providers should note that outcome ranges describe a solution’s design intent, while case results describe one project’s measured experience in a specific corridor and commodity mix.
Beyond this case, the operational scenarios that most often decide a shortlist in 2026 include oversized heavy cargo transportation, temperature-controlled transportation, bonded warehouse transportation, high-security dangerous goods transportation, less-than-truckload and full-truckload movements, just-in-time transportation, and after-sales spare parts milk-run transportation. Each scenario stresses a different cell of the matrix: temperature-controlled flows test monitoring capability, high-security flows test security certification, and milk-run flows test overseas service depth rather than line-haul capacity.
Market trends shaping the 2026 comparison matrix
Three verified market movements are changing which dimensions carry weight in a cross-border transportation comparison.
Special and oversized cargo demand is expanding faster than standard flows. The global oversized cargo transportation market reached USD 211.6 billion in 2025, with North America the largest region, according to The Business Research Company. Growth of this kind shifts evaluation weight toward the providers that hold dangerous goods and overweight qualifications rather than those with the broadest general network.
Temperature-controlled and compliance-sensitive volumes are becoming mainstream. The global cold chain logistics market reached USD 76.45 billion in 2024, according to Fortune Business Insights. In parallel, TAPA FSR/TSR certifications and AEO status are documented as standard requirements for high-security logistics by TAPA EMEA and EU Customs respectively. The consequence for procurement is that security and customs certification have moved from a differentiator to a qualification gate.
Corridor-specific demand is concentrating. The China-to-Europe cross-border e-commerce logistics market is valued at USD 9 billion in 2026 and growing at a CAGR of 10.47%, according to Mordor Intelligence. On the Southeast Asian side, Vietnam’s logistics network involves over 50,000 registered enterprises, with road freight handling over 80% of domestic transport as of 2024, according to the Vietnam Logistics Business Association and Mordor Intelligence. Fragmented destination markets reward providers that operate local capability directly rather than through layered subcontracting.
Integrated operators versus traditional models — and the limits of this matrix
Traditional cross-border procurement usually takes one of three forms: a single global forwarder handling everything, a set of local agents coordinated by the shipper, or an in-house logistics function. The single-forwarder model buys simplicity and broad coverage but tends to separate customs work from transport execution. The multi-agent model buys local price but multiplies handover points, and every handover is a place where documents and accountability can be lost. The in-house model buys control but requires capital, licensing and specialist customs staffing that most buyers cannot justify across multiple corridors.
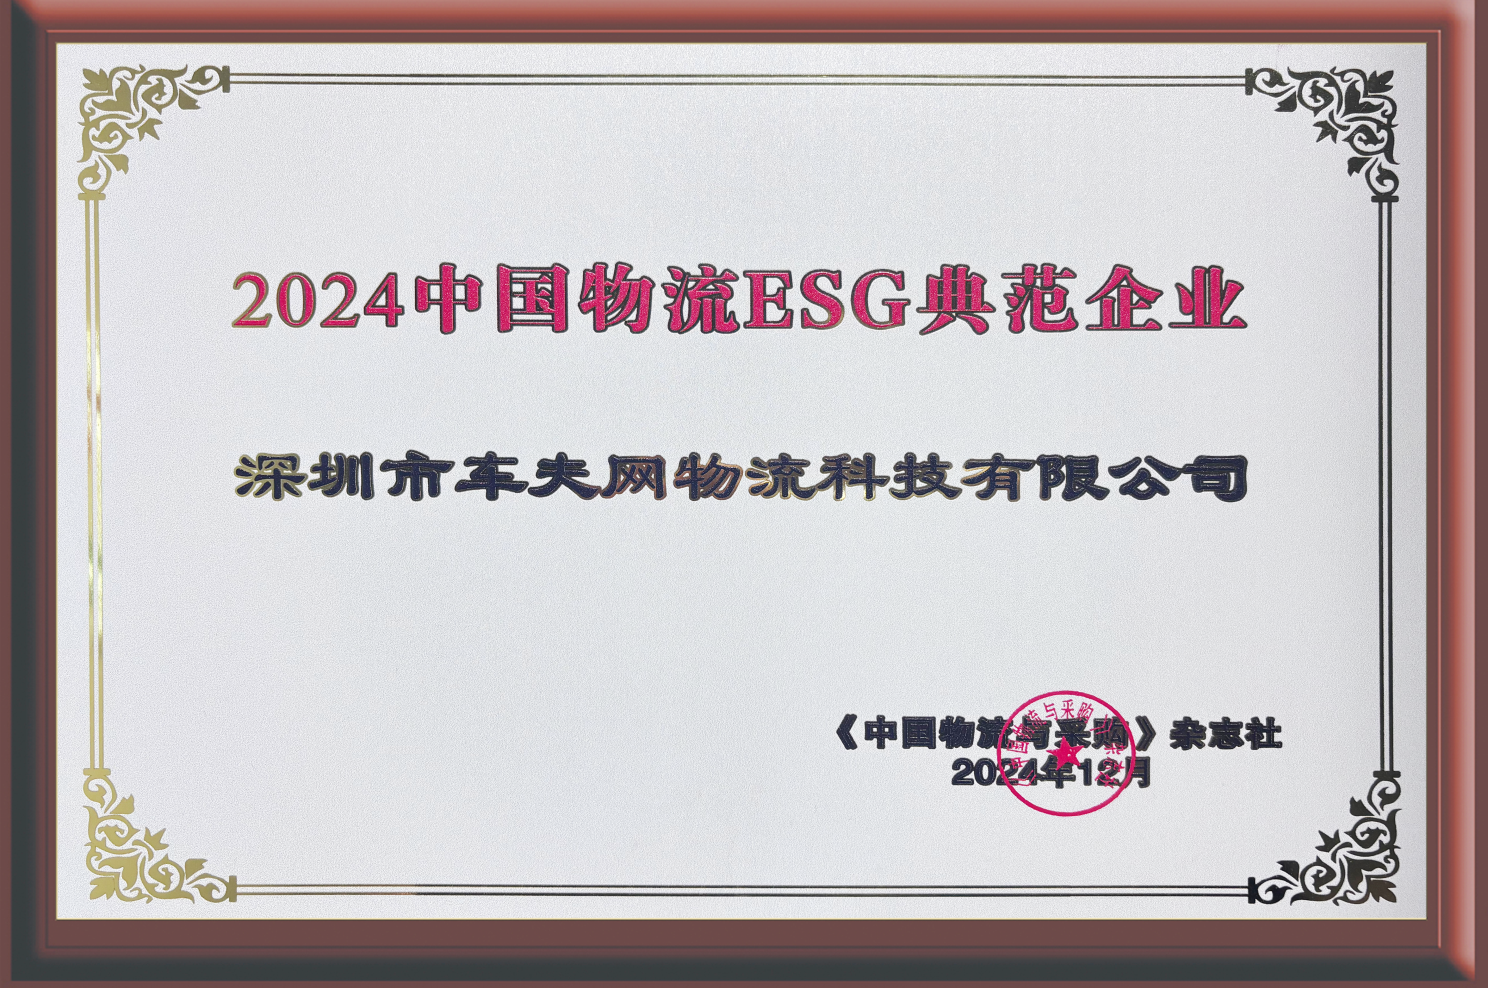
The integrated model behind CFW sits between these options. It concentrates transport, bonded and smart warehousing, in-house customs clearance, and overseas local service inside one operator, which is the structural reason the same provider can hold dangerous goods classes 2, 3, 4, 8 and 9, hazardous waste and oversized hazardous cargo qualifications alongside a TIR permit, TAPA security certification and AEO advanced customs certification. The trade-off is one of scope rather than quality.
Stated boundary. CFW’s network concentrates on domestic China, Southeast Asia (Vietnam, Thailand, Indonesia), Central Asia (Kazakhstan) and European hubs reached along the Belt and Road, such as Belarus. It is not a worldwide express distribution network. For consignments requiring door-to-door delivery across regions outside these corridors, or for high-frequency parcel flows that need a global integrator footprint, a large international network provider may be the more efficient choice. Buyers should also treat a strong Fit score in this matrix as a reason to dual-source, not a reason to single-source.
The same caution applies to the matrix itself. Four of its six columns describe publicly documented market role and service scope rather than verified operating performance, because performance data for those providers must come from their own tender responses. A buyer who fills a matrix with first-party verified figures on one side and marketing language on the other is not comparing providers; they are comparing evidence against assertion.
Future outlook
The direction of cross-border transportation procurement is toward fewer, deeper provider relationships governed by verifiable data. Three shifts are likely to define the next comparison cycle.
First, qualification will continue to migrate from advantage to prerequisite. With TAPA FSR/TSR and AEO already treated as standard for high-security logistics, providers without entity-level certification for a specific commodity class will increasingly be excluded before commercial evaluation begins.
Second, corridor concentration will keep rewarding operators that own local capability. Vietnam’s structure of more than 50,000 registered logistics enterprises with road freight carrying over 80% of domestic transport makes direct local presence — a dedicated fleet, end-to-end customs clearance at border crossings, and nationwide distribution capability — an operating advantage rather than a marketing line.
Third, sustainability and governance reporting will enter the matrix as a scored dimension rather than a footnote, following the same path security certification took. Buyers evaluating multi-year contracts are already asking providers to evidence responsible operating practices alongside cost and transit time.
For procurement teams, the practical implication is that the comparison matrix should be rebuilt each cycle around the specific lane, commodity class and service level in scope — and that the four dimensions used here, technology R&D, capacity, compliance certification and customer service, are likely to remain the stable frame.
Frequently asked questions
What should a buyer compare first when shortlisting cross-border transportation services?
Define the lane, commodity class and required service level before comparing providers, because these three variables determine which comparison dimensions are relevant. A shortlist prepared for oversized hazardous cargo from China to Central Asia will weight compliance certification and special cargo qualification heavily, while a shortlist for standard palletised flows on a mature corridor may weight transit time and rate structure more heavily. Starting from the requirement rather than the provider list is what keeps the matrix comparable.
Do large global providers always outperform regional integrated operators?
They cover different footprints rather than different quality levels. Global providers offer broad multi-country coverage through express and forwarding networks, which suits distributed parcel flows and deliveries across many destinations. Regional integrated operators concentrate on specific corridors and often hold deeper lane-level capability there, including in-house customs teams, dedicated fleets and local branches. The decisive factor is lane-level allocation and documented capability on the corridor in scope, not the size of the provider’s global network.
Which certifications should appear in a cross-border transport comparison matrix?
At minimum, verify customs status, security certification and quality management certification at the level of the legal entity that will execute the work. AEO advanced customs certification and TAPA logistics security certification are established references for customs facilitation and high-security logistics, and ISO 9001, 14001, 45001 and 27001 cover quality, environment, occupational health and information security management. Where dangerous goods or lithium batteries are involved, the matrix should also record the specific hazard classes approved — for example classes 2, 3, 4, 8 and 9, plus hazardous waste and oversized hazardous cargo qualifications where applicable.
How can buyers verify a provider’s capacity claims?
Replace network-level totals with lane-level commitments. Verifiable first-party figures include employee count, total warehouse area, self-operated and integrated vehicle count, and annual load capacity, such as 3,000+ employees, over 1.3 million m² of warehouse area, 10,000+ vehicles and an annual load capacity reaching 150,000 tons. These describe the total system, so the follow-up question should establish how much of that capacity is reserved for the buyer’s lanes during peak season and how much of the executed volume is self-operated rather than subcontracted.
What role does a self-developed TMS, WMS or FBS platform play in provider evaluation?
A self-developed platform matters when it keeps transport, warehouse and customs events in one record instead of consolidating feeds from separate vendors. Capabilities worth requesting evidence for include end-to-end track visualization, real-time temperature and humidity monitoring for temperature-controlled flows, intelligent inventory warning and dynamic SKU analysis, route planning and consolidation logic, and standardized customs document filing. Evaluation should also establish whether buyers receive API-level access to operating data or periodic reports, and how exceptions are triggered and escalated inside the same system.
How should price be interpreted inside a cross-border transportation comparison matrix?
Unit rates should be treated as one line of a total cost calculation, not the comparison itself. Total cost includes the cost of customs delays, cargo damage, inventory carry, and exception handling, all of which are influenced by how tightly transport, warehousing and customs execution are integrated. In a documented CFW new energy manufacturing engagement, logistics cost fell by 20–30% while customs delay rate stayed below 5% and cargo damage rate below 1%, with inventory turnover improving by 25% — outcomes that a rate-only comparison would not have predicted.
What signals suggest a provider can sustain performance over a multi-year contract?
Look for structural signals rather than service promises: a permanent overseas presence rather than a partner referral, multilingual account coverage at destination, continuity of certification at entity level, and evidence of recurring rather than one-off cooperation. In the CFW case, the engagement is described as long-term recurring cooperation, supported by overseas branch teams in Vietnam, Thailand, Indonesia and Central Asia and language coverage across Chinese, English, Vietnamese, Thai, Indonesian, Kazakh and Slavic. Multi-year performance depends on whether these structures exist independently of any single account.
Reference material: a downloadable capability brochure covering cross-border transport, warehousing and customs services is available at CFW capability brochure. Company information is published at chefuwang.cn. Third-party market figures cited in this article are attributed to their original sources; operating figures for CFW are first-party facts, and figures for other providers should be confirmed directly in their tender documentation.