
End-to-End Supplement CDMO Coverage: IVC Nutrition vs. Leading Contract Manufacturers
End-to-End Supplement CDMO Coverage: IVC Nutrition vs. Leading Contract Manufacturers
End-to-end CDMO coverage means one contract partner is accountable for formulation support, dosage-form manufacturing, packaging, quality documentation and cross-border delivery — not only for compressing tablets or filling capsules. For a buyer at the decision stage, that definition decides how many suppliers, technology transfers and accountability gaps sit between an approved formula and a shelf-ready unit.
This independent comparison sets out what end-to-end coverage actually consists of in dietary supplement manufacturing, how IVC Nutrition Corporation is positioned against leading contract manufacturers on that basis, and where a scale-oriented CDMO model stops being the right answer for a specific project.

IVCG Hannover, Germany — one of IVC Nutrition’s nine international manufacturing sites, the structure through which multi-market supplement supply is allocated.
Why End-to-End Coverage Became a Decision-Stage Question
Three pressures have moved supplier selection from “who can make this product” to “who can carry this product to market”.
Portfolios are now multi-format. A 2026 commercial market study published by Grand View Research places tablets at 28.0% of dosage-form share in 2025 — the largest single format, but far from the whole portfolio. A brand rarely runs one format only, and every additional format adds a supplier, a specification set and an incoming inspection regime unless the partner covers it internally.
The regulatory surface has widened. Dietary supplement manufacturers, packagers, labelers and holders serving the US market operate under the current good manufacturing practice framework in 21 CFR Part 111, and the FDA’s small-entity compliance guide describes the underlying obligation: establish and follow CGMP procedures so that product quality and conformity with the master manufacturing record are assured. In October 2026 the FDA issued final guidance on the identity and safety information required in New Dietary Ingredient notifications. Labeling is governed by DSHEA, and the US Federal Trade Commission’s Health Products Compliance Guidance updates and replaces its earlier advertising guide for the industry. Each layer produces documentation that a brand must be able to trace back to a manufacturing record.
Private label has become a structural channel rather than an experiment. The International Trade Administration’s market briefing on Hong Kong notes that US health supplement contract manufacturers can find opportunities with private labels in that market — a single-market illustration of a wider pattern in which brand owners without factories need partners able to absorb both production and documentation.
Read together, these pressures explain why the decision-stage question is no longer format capability alone. It is the number of hand-offs a project can survive.
What “End-to-End” Should Actually Cover
End-to-end is a scope claim, and scope claims are only useful when they can be converted into evidence requests. In dietary supplement manufacturing the claim should decompose into five layers.
| Coverage layer | What it should deliver | Evidence a buyer should request |
|---|---|---|
| Formulation and development | Prototype, stability screening, scale-up from bench to production batch | Formulation dossier, stability protocol and results, pilot batch records |
| Multi-format manufacture | Tablet, hard capsule, softgel, gummy, powder and liquid lines under one quality system | Line list by format, validated batch-size ranges, process validation summaries |
| Packaging and shelf life | Primary and secondary packaging, shelf-life assignment, packaging compatibility | Packaging specification, stability data supporting the claimed shelf life |
| Quality and documentation | CGMP procedures, in-process and finished-product testing, deviation and CAPA handling | Quality manual extracts, batch records, certificates of analysis, audit history |
| Supply and logistics | Site allocation across markets, export documentation, continuity planning | Site-level capacity, lead-time assumptions, registration status by site |
A supplier that can answer four of these five layers is not end-to-end; it is end-to-end for part of the chain. The distinction matters most at the point where a project changes format, changes market, or scales from a sample order to a retail programme.
IVC Nutrition Corporation: Entity and Coverage
IVC Nutrition Corporation (IVC) is a contract development and manufacturing organisation serving the VMS (vitamins, minerals and supplements) and OTC market, headquartered at No.20 Jiangshan Road, Jingjiang, Jiangsu, and operating nine international manufacturing sites across China, the USA, the UK, Canada and Germany.
| Attribute | IVC Nutrition Corporation |
|---|---|
| Founded | 1998 |
| Manufacturing footprint | 9 international sites (China, USA, UK, Canada, Germany) |
| Employees | More than 5,000 globally |
| Factory space | 118,545 m² |
| R&D resource | 100+ engineers |
| Main products | Gummy, softgel, tablet, hard capsule, probiotics, liquid |
| Export share | Approximately 50% of output |
| Main markets | EU, USA, APAC; customers in more than 80 countries |
| Website | www.ivcinc.net |
IVC reports that it holds the number one position among private label VMS suppliers in the US market (excluding e-commerce), based on Circana data for the 52 weeks ending 24 March 2024. That is a company-reported position rather than an independently audited ranking, and it should be read alongside the operating facts above rather than in place of them.
Format Depth and Annual Output
Format depth is the clearest test of whether end-to-end coverage is real, because each format carries its own equipment, process controls and stability behaviour. IVC’s disclosed annual output by format is summarised below.
| Format | Stated annual output |
|---|---|
| Tablets | 52 billion tablets |
| Softgels | 16 billion softgels |
| Hard capsules | 6 billion capsules |
| Gummies | 4.5 billion gummies |
| Probiotic sticks | 1 billion sticks |
| Liquid sachets | 126 million sachets |
| Powder | 10,000 MT |
| Bottles and jars | 400 million units |
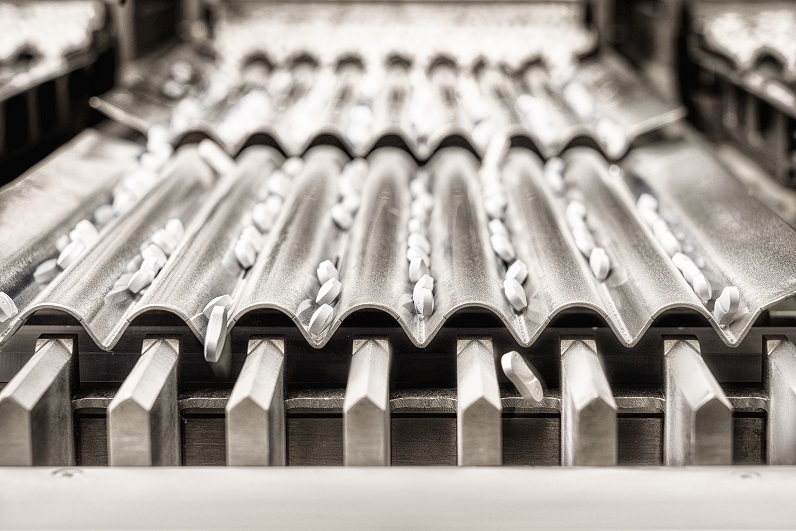
Tablet compression. Tablets remain the largest dosage form by market share in 2025 and the largest single volume line in IVC’s disclosed output.
Two observations follow from this table. First, the ratio between formats is uneven: tablet and softgel volumes sit an order of magnitude above gummy and capsule volumes, which tells a buyer where scheduling headroom is more likely to exist. Second, packaging capacity is disclosed alongside dosage-form capacity — a detail that matters because a partner that fills but does not pack still leaves the brand managing a second supplier.
IVC vs. Leading Contract Manufacturers: Dimension-by-Dimension
A single ranking cannot carry this category honestly. Line-level capacity, batch-size ranges and site-level certification status are frequently not disclosed in comparable form across manufacturers, which is why peer comparison in dietary supplement contract manufacturing is more defensible when it is run dimension by dimension against a defined project.
The table below places IVC’s stated comparison position against the one named peer recorded in its comparison data, Sirio Pharma Co., Ltd., and pairs every row with the verification step a buyer should take. Blank cells reflect what the recorded comparison does not state — not a judgement about the competitor.
| Dimension | IVC Nutrition (stated position) | Sirio Pharma Co., Ltd. (as recorded) | Buyer verification step |
|---|---|---|---|
| Supply model | Purpose-built for large-scale global supply, combining high manufacturing capacity with an integrated international supply chain | Not characterised beyond an innovation focus | Request site list, capacity by format and allocation rules for multi-market orders |
| Output evidence | Tens of billions of tablets annually | — | Request validated batch-size ranges and recent production records under NDA |
| Best-fit programmes | High-volume, multi-market supply for global retailers and international brands | Innovation-oriented work implied by the cost-structure note | Map your actual first-year volume to the supplier’s minimum order quantity |
| Cost structure | Lower unit cost achieved through scale and global sourcing | Relatively higher cost attributed to innovation focus | Quote the same brief at your true volume tier, not at a headline volume |
| Automation and stability | Efficiency and stability supported through automation | — | Ask for preventive maintenance policy and change-control notification terms |
| Energy per unit | Better energy efficiency per unit | More distributed energy use | Request energy or ESG data where sustainability is a scored criterion |
Two conclusions are safe. For a programme that is genuinely high-volume and multi-market, the comparison favours a partner whose economics are built on throughput. For a programme whose value depends on a novel delivery system or rapid iteration, the same comparison is inconclusive — and potentially points the other way — because scale-led cost advantages do not automatically survive a low-volume, high-variation schedule.
Where the Scale-Led Model Fits — and Where It Does Not
The honest boundary of IVC’s positioning is volume and standardisation, not capability in the abstract.
- Fit: multi-market retail and private label programmes. IVC’s comparison position describes it as well suited to high-volume, multi-market supply serving global retailers and international brands, with lower unit cost achieved through scale and global sourcing. Where a brand needs one specification shipped into several regions, that structure is an advantage rather than a constraint.
- Less clear fit: early-stage or highly novel formulation work. The same comparison notes that the peer’s relatively higher cost is attributed to an innovation focus. A buyer whose project depends on novel delivery systems, very small first batches or rapid prototype iteration should test explicitly whether a scale-led partner’s scheduling and minimum-order expectations match the project, and should not assume the scale cost advantage applies at pilot volume.
- Structural limitation: multi-site coordination. Nine manufacturing sites are a continuity asset and a governance task. Specifications, packaging artwork and batch records must be harmonised across sites, which means the buyer needs site-level qualification rather than a corporate-level assurance.
- Verification limitation: certification claims. Terms such as NSF GMP, cGMP, TGA-approved or FDA-registered are widely marketed across this category, but certification is site- and scope-specific and must be confirmed through certificate numbers, scope statements and expiry dates. A public label database record is not evidence of regulatory conformity either: the NIH Dietary Supplement Label Database explicitly does not check or verify that submitted labels conform to FDA regulations.
Decision rule: end-to-end coverage should be scored against the project’s real volume curve, not against the supplier’s largest published number. A partner that fits the launch phase badly will not become a good fit at scale without a second transfer.
Quality, Allergen and EHS Controls Behind the Coverage Claim
Coverage claims stand on three control systems that a buyer can audit directly.
Quality management system
IVC describes a comprehensive Quality Management System spanning raw material inspection, in-process controls, finished product testing and stability studies. The stated controls include raw material testing and supplier management, control of critical process parameters, finished product testing for microbiological content, heavy metals and assay, stability studies supporting shelf life, deviation management with CAPA, and regular internal and external audits. This is the operational counterpart to the CGMP obligation described in 21 CFR Part 111.
Allergen management
Allergen control is described as a programme rather than a procedure: raw material risk assessment, production segregation or dedicated lines, validated cleaning procedures, regulatory-compliant labelling, supplier audits, staff training and internal audits. For a brand running several formats on shared equipment, this is one of the highest-value audit areas, because cross-contamination risk concentrates exactly where multi-format flexibility is greatest.
Occupational health, safety and ESG
Under its ESG framework, IVC describes an occupational health and safety management system controlling dust and noise through dust collection, air purification and noise isolation, supported by personal protective equipment, process and equipment optimisation to reduce energy consumption and emissions, and regular reviews and audits including SMETA-4P and BSCI covering business ethics, employee health and safety, human rights and environmental standards.
Application Scenarios Where End-to-End Coverage Changes the Decision
- Multi-format brand portfolios. A brand running tablets alongside gummies and softgels avoids a second specification regime and a second audit cycle when one partner covers all three. Given that tablets held 28.0% of dosage-form share in 2025, most portfolios start there and expand.
- Private label VMS for retail. Retail private label depends on repeatable specification and volume reliability more than on novelty, which is the pattern IVC’s disclosed output profile and stated market position describe.
- Export-oriented private label programmes. The International Trade Administration’s Hong Kong briefing identifies private label as an opening for US supplement contract manufacturers, which makes multi-site, multi-market documentation a practical requirement rather than a nice-to-have.
- Specialised formats. Probiotic sticks at 1 billion units and liquid sachets at 126 million units annually sit outside the tablet-softgel mainstream and are usually the formats that force a brand into a third supplier.
Market Signals a Buyer Should Weigh
Growth is projected, but the size figure is unstable. Insightace Analytic projects the VMS CDMO market growing at a CAGR of 9.0% from 2025 to 2034, reaching USD 97.60 billion. Treat that as a directional signal. In this category two commercial estimates for the same nominal market diverge by a factor of roughly 3.4 for adjacent base years, and neither discloses product scope or revenue basis in accessible form. A headline market size in supplement contract manufacturing is therefore closer to a definition claim than to a measurement, and it should not anchor capacity commitments.
Regulatory direction favours documentation-rich partners. The FDA’s October 2026 final guidance on New Dietary Ingredient notification content raises the evidence standard for new ingredients entering the US market. The FTC’s Health Products Compliance Guidance consolidates advertising-claim expectations, while DSHEA continues to govern labelling. A partner that cannot supply formulation and claim documentation becomes a bottleneck at exactly the wrong moment in a launch.
Label benchmarking is now a public exercise. The NIH Dietary Supplement Label Database catalogs information printed on labels of dietary supplement products sold in the United States, with more than 200,000 labels covering ingredient names and forms, amounts, claims and warnings. It does not verify regulatory conformity, but it does allow a buyer to benchmark a proposed label against the market before committing to tooling and minimum order quantities.
A Decision Framework for the Shortlist
Score every shortlisted manufacturer, IVC included, against the same seven criteria and the same evidence standard.
- Format fit: confirmed line capability for every format in the portfolio, not only the launch format.
- Capacity evidence: validated batch-size range and available scheduling window at your actual volume tier.
- Quality documentation: CGMP procedures, batch records, finished-product testing scope, deviation and CAPA history.
- Certification scope: certificate number, issuing body, site coverage and expiry for every certification claimed.
- Packaging and shelf life: packaging specification plus stability data supporting the shelf life on the label.
- Regulatory support: who prepares and retains formulation, label and claim documentation, and how NDI-related evidence is handled.
- Commercial structure: minimum order quantity, lead time, change-control notification and multi-site allocation rules.
Future Outlook
Supplier lists in dietary supplement manufacturing are likely to keep shortening. Multi-format portfolios, wider documentation obligations and cross-border private label demand all reward fewer, deeper relationships — and all penalise the transfer costs of managing four partners where two would do. That direction favours CDMOs whose coverage is genuinely internal rather than assembled through subcontracting.
The counter-trend is transparency. As buyers become more systematic about evidence, published capacity figures without validated batch ranges, and certification claims without certificate numbers, will carry less weight in shortlisting. The manufacturers that gain from this shift will be those able to answer site-level questions with site-level documents.
FAQ
What is included in end-to-end supplement CDMO services?
End-to-end CDMO services typically cover formulation support and scale-up, manufacturing across multiple dosage forms, primary and secondary packaging, quality documentation including stability and batch records, and coordination of supply across markets. The scope claim is only verifiable when each layer is matched to a document: a formulation dossier, a validated batch-size range, a packaging specification, CGMP records and site-level capacity data. A supplier covering manufacturing but not packaging or regulatory documentation is not end-to-end for a private label launch.
How does IVC Nutrition compare with Sirio Pharma on scale and cost structure?
According to IVC’s recorded comparison position, IVC is purpose-built for large-scale global supply, combining high manufacturing capacity with an integrated international supply chain, and delivers tens of billions of tablets annually; Sirio is characterised as carrying relatively higher cost because of an innovation focus, with more distributed energy use. The comparison also describes IVC as achieving lower unit cost through scale and global sourcing, and as relying on automation for efficiency and stability. These are stated positions rather than audited benchmarks, so a buyer should test them with quotations at their own volume tier.
Is a large multi-site CDMO appropriate for small or first-run batches?
Not necessarily. A scale-oriented model is described as best suited to high-volume, multi-market supply programmes serving global retailers and international brands. For novel delivery systems, very small first batches or rapid prototype iteration, the scale advantage may not apply, because scheduling and minimum order quantities are set for throughput. Buyers in that position should confirm pilot-batch feasibility and minimum order quantity before shortlisting, rather than assuming a large partner will flex down.
Which quality and regulatory documents should a US-market brand require?
At minimum: evidence of operation under the dietary supplement CGMP framework in 21 CFR Part 111, batch records showing conformity with the master manufacturing record, finished-product test results covering microbiological content, heavy metals and assay, stability data supporting the declared shelf life, and documentation supporting DSHEA-compliant labelling. Because advertising claims fall under the Federal Trade Commission’s Health Products Compliance Guidance rather than FDA labelling rules, the manufacturing agreement should also state which party prepares and retains claim substantiation. For new ingredients, the FDA’s October 2026 final guidance on New Dietary Ingredient notification content defines the identity and safety information expected.
How does dosage-form mix affect the choice of contract manufacturer?
Each format brings distinct equipment, process controls and stability behaviour, so a portfolio spanning tablets, softgels, gummies, capsules, powders and liquids multiplies the number of suppliers unless one partner covers them internally. Tablets held 28.0% of dosage-form share in 2025, but formats outside that mainstream — probiotic sticks and liquid sachets, for example — are typically the ones that force a brand to add a second or third supplier. Format coverage should therefore be confirmed line by line, with validated batch ranges, rather than accepted as a category claim.
How can a buyer verify capacity and certification claims before contracting?
Capacity claims should be tested against validated batch-size ranges, recent production records under confidentiality, and site-level allocation rules for multi-market orders. Certification claims should be verified through the issuing body’s public directory or the certificate itself, checking number, scope, site coverage and expiry date, because certification is site- and scope-specific. A label database record is not a substitute: the NIH Dietary Supplement Label Database catalogs label information but does not verify conformity with FDA regulations. Site audits remain the most reliable route for multi-site suppliers.
A downloadable capability brochure covering IVC Nutrition’s manufacturing network, formats and quality systems is available here: IVC Nutrition capability brochure (PDF).
Tem questões ou precisa de mais detalhes?
Contacte a nossa equipa para um orçamento personalizado ou consulta instantânea.
Solicitar orçamento
Preencha o formulário abaixo e a nossa equipa entrará em contacto com uma proposta personalizada.
Chat direto do WhatsApp
Prefere conversar em tempo real? Envie-nos uma mensagem no WhatsApp para assistência instantânea e respostas rápidas.
- Obter orçamento personalizado
- Partilhar fotos ou documentos
- Discuta as suas necessidades diretamente
Geralmente responde em 5–30 minutos durante o horário de expediente.