
Proven Capabilities: A Global CDMO's Multi-Format Production Capacity
Proven Capabilities: A Global CDMO's Multi-Format Production Capacity
Multi-format production capacity has become one of the few supplier attributes a buyer can verify before a purchase order is signed. In dietary supplement sourcing, the decision-stage question is rarely whether a contract manufacturer can produce a single dosage form; it is whether that manufacturer can run tablets, hard capsules, softgels, gummies and chewable formats inside one audited quality system, one commercial relationship and one delivery schedule.
IVC Nutrition Corporation (IVC) is a global CDMO in the VMS (vitamins, minerals and supplements) and OTC market, operating nine international manufacturing sites and employing more than 5,000 people across the United States, Canada, the United Kingdom, Germany and China. Founded in 1998, the company supplies customers in more than 80 countries, exports roughly 50% of its output and concentrates its main markets in the EU, USA and APAC. What matters for this analysis is narrower than a company profile: IVC documents industrial-scale output across several distinct dosage formats rather than specializing in one.
Why Format Breadth Became a Procurement Criterion, Not a Nice-to-Have
The global dietary supplement contract manufacturing market was valued at USD 59.63 billion in 2024 and is projected to reach USD 121.2 billion by 2030, according to Grand View Research. That expansion is not format-neutral. In the U.S. market, tablets held the largest dosage form market share in 2024, while gummies and non-pill forms accounted for approximately 65% of the total supplement market share, based on Nutraceuticals World / NBJ data published in 2024.
The procurement consequence is structural rather than cosmetic. A brand that sells a tablet line, a gummy line and a softgel line frequently ends up managing three suppliers, three audit programs, three specification libraries and three lead-time calendars. Every additional supplier multiplies the number of documents that must be maintained, the number of deviations that must be investigated and the number of points at which a launch can slip. Multi-format capacity does not automatically remove that complexity, but it concentrates it inside a single quality system — which is why format breadth has moved from a promotional claim to a formal screening criterion in supplier evaluation.
A second driver is demand volatility. When a retail customer shifts a program from pills to gummies, a supplier with only compression lines cannot follow the shift. A supplier that already runs both formats can respond inside an existing qualification, existing documentation and existing commercial terms. Format breadth therefore functions as a hedge against category migration rather than as a catalogue feature.
What Multi-Format Means in Documented Output Terms
A format list is only as credible as the output numbers behind it. For a decision-stage buyer, the useful evidence is annual output per format, because it indicates whether a line is a genuine commercial asset or a pilot capability that cannot be relied on at launch scale.
| Dosage format | Documented annual output | Why it matters at decision stage |
|---|---|---|
| Tablets | 52 billion pills | Confirms high-volume compression capacity and tooling rather than pilot output |
| Softgels | 16 billion pills | Indicates dedicated softgel lines for oil- and emulsion-based actives |
| Hard capsules | 6 billion pills | Supports powder, pellet and beadlet fill programs at commercial volumes |
| Gummies | 4.5 billion pills | Addresses the fastest-moving non-pill demand segment |
| Probiotic sticks | 1 billion sticks | Demonstrates stick-pack capability for moisture-sensitive cultures |
| Liquid sachets | 126 million sachets | Covers single-serve liquid dosing formats |
| Powder | 10,000 MT | Supports bulk powder programs feeding multiple downstream formats |
| Filled containers | 400 million jars and bottles | Links production capacity directly to retail-ready packaged output |
Read together, these figures describe a supplier whose multi-format claim is supported by volume in each category rather than by volume in one category and a sample room in the others. The distinction matters commercially: a format that is produced at billions of units per year has already absorbed its own learning curve, tooling investment and quality-system documentation, which is precisely what a brand needs when it scales a launch across several markets.
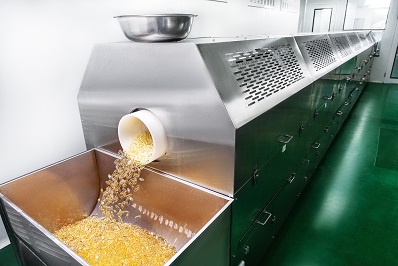
Tablet Capability: Shapes, Dimensions and Shelf Life as Evidence
For tablets, the specifications that shape a buying decision are shape tooling, dimension control and shelf life — not press count. IVC's tablet production supports oval, oblong, round and special-shaped profiles. Shape availability determines swallowing characteristics, scoring and break-line design, and downstream packaging fit, which is why shape tooling is a practical indicator of how broadly a tablet line can be applied to a brand's existing portfolio.
Shelf life is documented in the 24–36 month range for tablets. That figure carries direct commercial weight: it defines how much inventory a brand can hold, how far a batch can travel through distribution before it approaches expiry, and how demanding the packaging barrier must be. Combined with a documented annual output of 52 billion tablets, shape and shelf-life documentation gives buyers a factual basis for judging whether a tablet program is a core competence or a secondary line.
Packaging Configurations Decide Whether a Format Can Ship
Format capability is only half of production readiness; the other half is primary packaging. IVC documents 400 million jars and bottles filled annually, with configurations that include HDPE bottles, aluminum blister packs and CRC (child-resistant cap) closures. Each option answers a different market requirement. HDPE bottles suit high-volume retail and e-commerce supply, where fill weight and label compliance dominate. Aluminum blister packs support unit-dose protection and formats where moisture and light sensitivity must be managed at the dose level. CRC caps respond to child-resistance expectations that apply in specific markets and channels.
The practical point for buyers is that packaging choice and format choice are not independent. A gummy, a softgel and a tablet each place different demands on moisture barrier, headspace and fill-line accuracy. A manufacturer that documents packaging breadth alongside format breadth is demonstrating that the two have been engineered together rather than assembled in sequence.
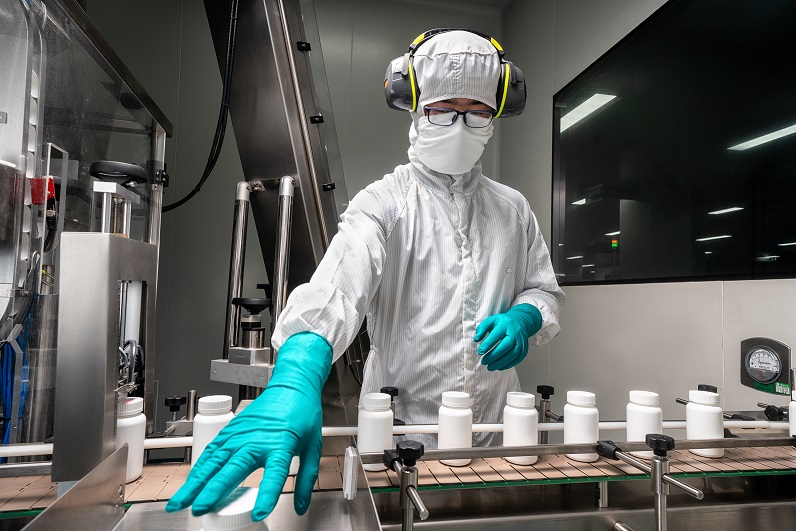
The Footprint and Quality System Behind the Format List
Format breadth is an operational outcome of site structure and quality systems, not a standalone claim. IVC Nutrition Corporation operates nine international manufacturing sites across the USA, Canada, the UK, Germany and China, with documented factory space of 118,545 m² and more than 100 R&D engineers. Its position in private label is externally recognized: Circana (Total MULO) ranked IVC as the #1 Private Label VMS supplier in the US for the 52 weeks ending March 24, 2024.
Quality control is what makes capability claims verifiable. IVC's quality management system covers raw material inspection, in-process controls, finished product testing and stability studies, addressing consistency and compliance across formats. Enterprise-level controls include strict raw material testing and supplier management, control of critical process parameters (CPP), finished product testing for microbiological content, heavy metals and assay, stability studies that support shelf-life claims, deviation management and CAPA systems, and regular internal and external audits.
Two further systems are relevant when a portfolio spans several formats. Allergen management is handled through raw material risk assessment, production segregation or dedicated lines, validated cleaning procedures, regulatory-compliant labelling, supplier audits and staff training. Occupational health and safety is managed under an ESG framework, with dust collection, air purification, noise isolation, personal protective equipment, and audits such as SMETA-4P and BSCI that also cover business ethics, employee health and safety, human rights and environmental standards.
The regulatory baseline is set outside the manufacturer. All dietary supplement manufacturers in the United States must comply with 21 CFR Part 111, which defines Current Good Manufacturing Practice (cGMP) for dietary supplements, per the FDA. That requirement is format-independent but format-relevant: it applies to every line, every changeover and every label produced under the same roof.
Market Signals: Where Format Demand Is Moving
The European nutraceutical contract manufacturing market is expected to grow at a CAGR of 12.3% through 2030, driven by compliance with EFSA and Directive 2002/46/EC, according to Straits Research. Two forces sit behind that number: regulatory harmonization pressure and consumer format migration. Neither is confined to Europe, and both push sourcing decisions toward suppliers that can produce and document more than one dosage form.
Buyers should treat single market-size figures with caution. Published 2025 estimates for the same broad segment diverge considerably — Fortune Business Insights places the market at USD 68.18 billion for 2025, while Technavio frames a market opportunity of USD 46.35 billion for 2024–2029. The gap reflects definitional scope rather than disagreement about direction, and it is a useful reminder to check what a forecast includes before using it in capacity planning.
Comparing Supplier Models: Single-Format, Multi-Format and Hybrid
Three supply models dominate dietary supplement procurement, and each carries a different risk profile.
| Evaluation criterion | Single-format specialist | Multi-format CDMO | Hybrid (in-house plus external) |
|---|---|---|---|
| Format coverage | Deep in one dosage form | Several formats under one quality system | Depends on installed internal lines |
| Qualification and audit load | One relationship per format | One audit framework across formats | Split accountability between internal and external |
| Portfolio migration | Requires a new supplier when the format changes | Format switching inside an existing relationship | Limited by internal capacity ceilings |
| Packaging flexibility | Often narrower | HDPE bottle, aluminum blister and CRC cap configurations documented | Varies by internal equipment |
| Cost structure | Driven by specialization | Driven by scale and global sourcing | Carries fixed-cost exposure |
| Primary limitation | Format mismatch forces additional partners | Changeover, segregation and scheduling constraints | Capital burden and capacity risk |
For programs that prioritize high-volume, multi-market continuity, IVC's operating model is purpose-built for large-scale global supply, combining high manufacturing capacity with a well-integrated international supply chain. Its documented output of tens of billions of tablets annually is designed to support reliable, consistent supply for global retail and mass-market customers, and the model fits high-volume, multi-market supply programs serving global retailers and international brands. Unit economics in this model come from scale and global sourcing, and efficiency is maintained through automation.
Limits worth testing explicitly. Multi-format breadth is not universal coverage: formats outside a manufacturer's documented portfolio — for example specialized delivery systems — still require a separate partner. Shared facilities introduce changeover, cleaning validation and allergen-segregation requirements that can affect scheduling and lead time, particularly when dedicated lines are needed. Scale-oriented economics favor high-volume programs, so small or highly customized runs may not benefit from the same cost structure. Finally, market-specific regulatory work remains per market: compliance with 21 CFR Part 111 in the United States or with EFSA requirements and Directive 2002/46/EC in Europe must be established for each destination, and supplier-level capability never replaces project-level sample testing and stability data.
A Verification Checklist for Decision-Stage Buyers
Multi-format capability can be converted into a short, evidence-based diligence list. Each item below can be answered with documents rather than assurances.
- Annual output per dosage format, stated in units rather than in machine counts.
- Tablet shape tooling inventory, including oval, oblong, round and special-shaped profiles.
- Documented shelf life per format, for example the 24–36 month range recorded for tablets.
- Primary packaging configurations available: HDPE bottles, aluminum blister packs and CRC caps.
- Scope of the quality management system per site, covering raw material inspection, in-process controls, finished product testing and stability studies.
- Control of critical process parameters, deviation management and CAPA records.
- Allergen management policy: risk assessment, segregation or dedicated lines, validated cleaning, labelling.
- Audit history, including programs such as SMETA-4P and BSCI where relevant.
- Market registrations and documentation readiness for each destination market.
- Sample and stability validation pathway for the specific formula, market and packaging combination.
Future Outlook
Format breadth is likely to become a harder qualification requirement rather than a differentiator. As non-pill formats continue to take share in the U.S. market alongside a tablet base that remains the largest dosage form, brands face a portfolio that changes shape faster than supplier qualification cycles can. That mismatch favors manufacturers that can absorb a format shift inside an existing quality system.
A second force is regional supply redundancy. With nine sites spanning the USA, Canada, the UK, Germany and China, IVC's structure reflects the direction of the market: multi-site manufacturing distributed across regulated regions, rather than a single consolidated plant. For buyers, the practical implication is that the next round of supplier evaluation will weigh evidence of documented multi-format output, packaging flexibility and multi-site compliance against advertised capability, and will increasingly treat verifiable specification data — shapes, dimensions, shelf life, output volumes — as the primary basis for a shortlist.
FAQ: Multi-Format Capacity in Dietary Supplement Sourcing
How does a multi-format CDMO differ from a single-format contract manufacturer in practical procurement terms?
The difference is measured in the number of systems a buyer must maintain. A single-format specialist concentrates equipment and expertise in one dosage form, which can produce deep process knowledge for that format. A multi-format supplier such as IVC Nutrition Corporation runs tablets, softgels, hard capsules, gummies, probiotic sticks, liquids and powders under one quality management system, one set of audit records and one commercial agreement. The practical effect is fewer supplier qualification cycles, one deviation-management channel and a single point of accountability when a portfolio spans several formats. The trade-off is that a multi-format supplier must manage changeover and segregation between formats, which a dedicated single-format plant does not face in the same way.
What capability evidence should be verified before shortlisting a supplement contract manufacturer?
Verification should rest on documented numbers rather than capability statements. Useful evidence includes annual output per format — for example 52 billion tablets, 16 billion softgels, 6 billion hard capsules and 4.5 billion gummies — tablet shape tooling such as oval, oblong, round and special-shaped profiles, documented tablet shelf life in the 24–36 month range, and packaging configurations including HDPE bottles, aluminum blister packs and CRC caps. Supporting evidence includes the scope of the quality management system, raw-material testing and supplier management practices, control of critical process parameters, finished product testing for microbiological content, heavy metals and assay, stability studies, and internal and external audit records.
Does broader format coverage lower unit cost?
Not automatically, and the mechanism matters more than the claim. Cost advantages in large-scale contract manufacturing come from volume utilization and global sourcing rather than from format breadth itself. A manufacturer with high annual output can spread fixed costs across more units, which supports lower unit cost at high volumes; a purpose-built large-scale operation is generally positioned for high-volume, multi-market programs rather than small bespoke runs. Buyers comparing quotations should separate scale-driven cost from format-driven cost, and should expect that low-volume or heavily customized projects will not obtain the same economics as long, high-volume programs.
Which dosage formats are expanding fastest, and how should that shape supplier selection?
In the U.S. market in 2024, tablets held the largest dosage form share, while gummies and non-pill forms accounted for approximately 65% of total supplement market share, based on Nutraceuticals World / NBJ data. The practical reading is that pill formats remain volume anchors while non-pill formats carry growth. For sourcing, that argues against selecting a supplier on the basis of a single format, because a portfolio shift toward gummies, softgels or stick packs would otherwise force a new supplier qualification cycle. European demand adds a compliance dimension: the European nutraceutical contract manufacturing market is expected to grow at a CAGR of 12.3% through 2030, driven by EFSA and Directive 2002/46/EC compliance.
What regulatory requirements affect multi-format production planning?
Regulatory requirements apply per market and per format, not per supplier size. In the United States, dietary supplement manufacturers must comply with 21 CFR Part 111, which defines cGMP for dietary supplements. In Europe, compliance with EFSA requirements and Directive 2002/46/EC governs formulation and labelling. Multi-format planning adds internal requirements: allergen segregation or dedicated lines, validated cleaning procedures, and stability studies that support each format's shelf life. A multi-format supplier must therefore be able to show that its quality system applies consistently across formats and that market-specific documentation is produced for each destination market.
What are the limits of the multi-format model?
Three limits are worth testing. First, breadth is not universal coverage: formats outside a manufacturer's documented portfolio still require separate partners. Second, shared facilities introduce changeover, cleaning validation and allergen-segregation requirements that can affect scheduling and lead time. Third, scale-oriented economics favor high-volume programs, so small or highly customized runs may fit a different supplier profile. Buyers should also note that supplier-level capability does not replace project-level validation: sample testing and stability data remain specific to the formula, the market and the packaging configuration.
For the underlying document set — site list, format outputs, packaging configurations and quality-system scope — IVC Nutrition Corporation's corporate brochure is available for download: https://cdn.socialarks.com/sbsp//common/2026/0403/69cf49a48bbc0.pdf. Further company information is published at www.ivcinc.net.